Microsoft's concrete bill comes due tonight
The openTonight two very different software balance sheets face the same question: is the cash turning into returns?
$MSFT: The best software franchise is now a capacity companyMicrosoft reports fiscal first quarter results today, Oct 28, after the close, and the demand side has never looked stronger. Fiscal 2026 revenue rose 18% to $331.84B. Microsoft Cloud revenue rose 27% to $214.40B, Azure and other cloud services grew 41%, and commercial remaining performance obligation rose 84% to $678B. The cash side tells a different story. Operating cash flow was $182.94B, but cash capex was $115.95B and new finance leases added $24.61B. Full capex reached $140.56B, or 76.83% of operating cash flow, up from 25% in fiscal 2017. After stock pay and other adjustments, owner cash fell to $17.31B from $43.20B in fiscal 2024. Our thesis: Microsoft has turned from a software company that happens to own data centres into a capacity company that happens to sell the best software. Superintelligence demand is supply constrained, so the build is probably the right call. But at an enterprise value of $3.90T, the market is asking owner cash to compound at 37.86% a year for ten years at a 9% discount rate. That only works if capex intensity falls as the build matures. The clearest early signal sits in Intelligent Cloud, where cost of revenue rose 44% against revenue growth of 30%. Tonight, watch whether that gap narrows, whether Azure holds near 40% growth, and whether the backlog converts fast enough to lift owner cash. Also reporting today: $QTWO, debt free and pitching itself as the governed gateway between bank customers' agents and their accounts. Read the $MSFT research Read the $QTWO research Quick hits
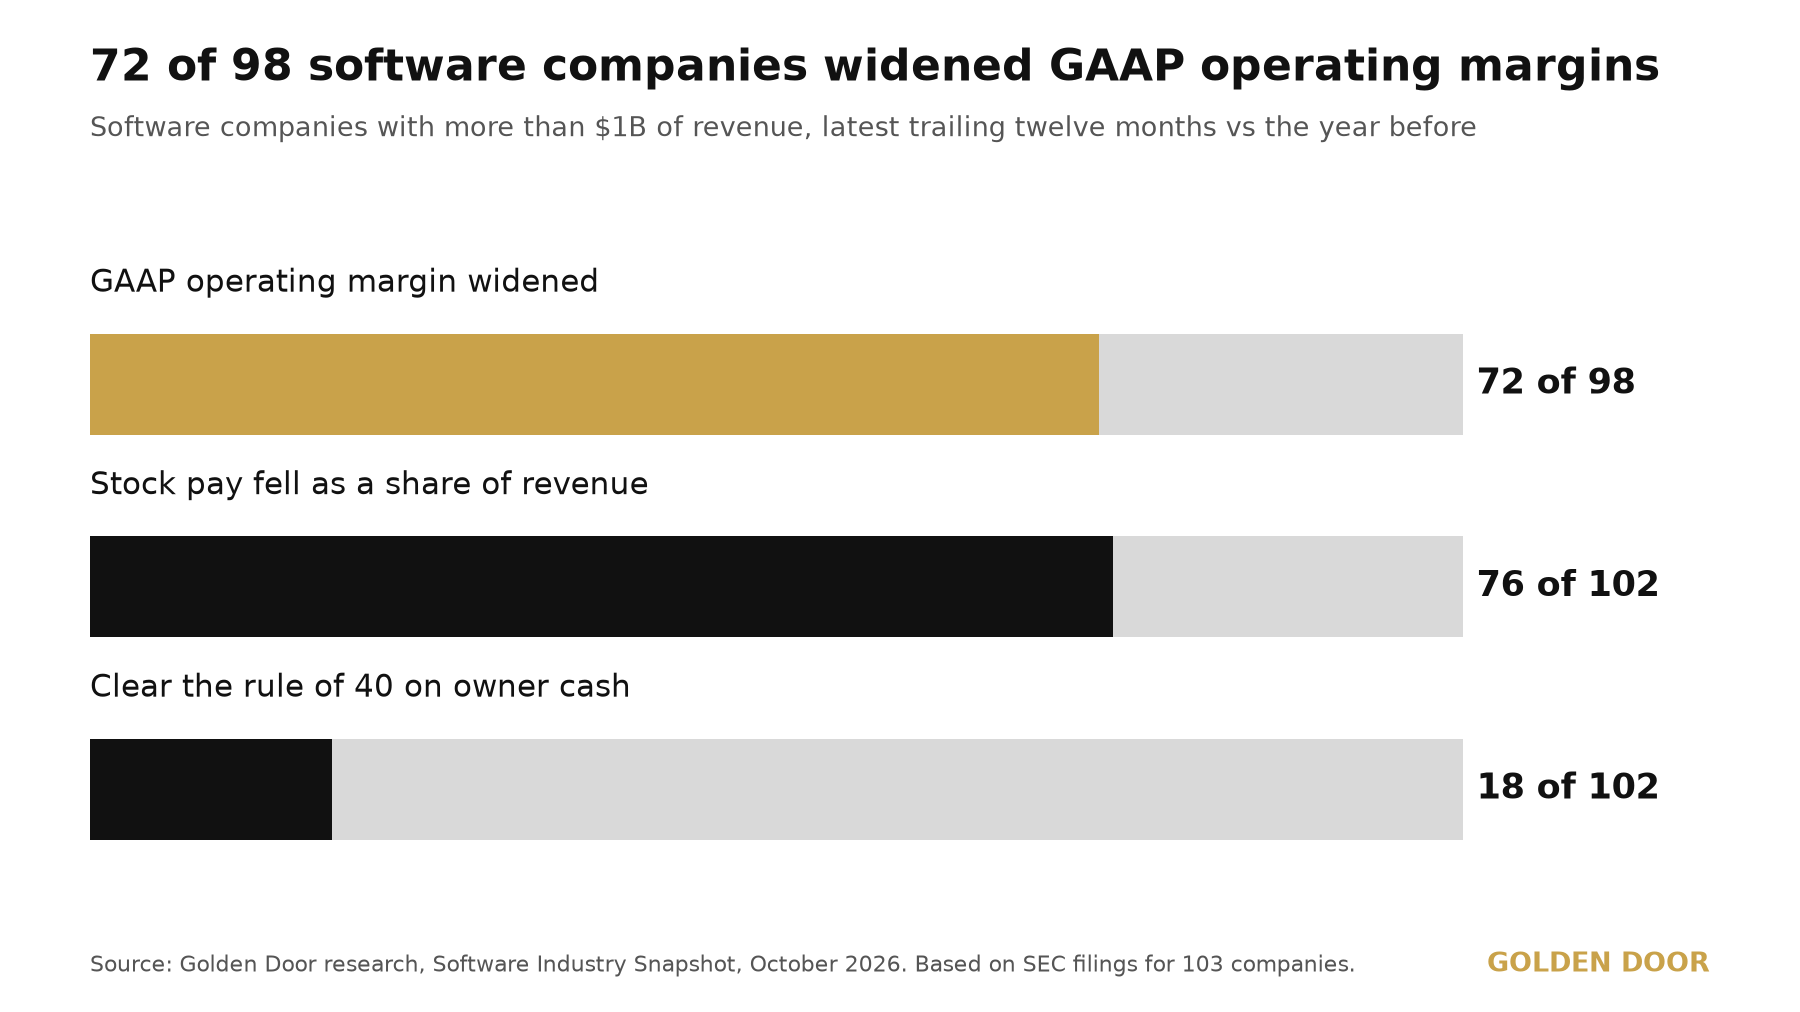
$GEN: Security is the new moat, but this one floatsObscurity used to be a moat. Autonomous agents now read every line and try every permutation, so security through obscurity is over. The same machines that probe for weaknesses can also patch them, which makes security one of the rare categories where more compute in means more value out. Platforms that enforce permissions, approvals and audit trails, like $BOX, now win on trust as much as on features. Gen Digital, which also reports after the close today, shows the economics at their best. It sells consumer cyber safety subscriptions at a 78.01% gross margin, with trailing revenue of $5.08B and a GAAP operating margin of 41.68%. Owner cash, after stock pay and capex, is $1.32B. The catch is the balance sheet. Debt principal is $8.23B, and $5.78B of it, or 70.23%, pays SOFR plus a margin. The filing prices that exposure: a 100 basis point move in SOFR changes annual interest by $58M. Interest expense was $124M in the latest quarter, down from $156M a year earlier, so the exposure cuts both ways. A 5.25x leverage covenant and a springing maturity sit over the revolver and Term A loan. What to watch: whether the $900M of 6.75% notes due Sep 30, 2027 can be retired from cash flow while the $1.50B revolver stays undrawn. In security, the moat is the product. The balance sheet decides who keeps the toll. $FIG: The second payroll is still bigger than the cashFigma's growth numbers are among the strongest in application software. Revenue grew 48.25% in Q2 to $370.08M, and $1.28B over twelve months. Net dollar retention is 136%, up from 129% a year ago. Customers paying more than $10K a year number 15,964, up 34%, and those above $100K number 1,635, up 46%. Then there is the second payroll. Stock pay over twelve months was $1.67B against operating cash flow of $249.25M. That is 671.29% of operating cash flow and 130.57% of revenue. Count stock pay as a cost and owner cash is negative. The trend is moving the right way. Stock pay fell from 50.68% of revenue in Q1 to 39.87% in Q2. The test is whether it stays below that line through the Q3 print on Nov 4 and into Q4, and whether retention holds above last year's 129%. Figma is an extreme case of an industry-wide pattern. Across 103 software companies with more than $1B of revenue, stock pay fell as a share of revenue at 76 of 102 names. Software is harvesting. But count stock pay as a real cost and the median owner cash margin is 12.62%, and only 18 of 102 names clear the rule of 40. Growth that looks free on an adjusted basis is often paid for in shares. By the numbers72 of 98Software companies with more than $1B of revenue whose GAAP operating margins widened over the past year. The margin story is real; the stock pay story is what decides who keeps it.
The model's read, not advice. Rebuild the numbers yourselfFull Access opens the Financial Engine: filed SEC statements, a 5-year DCF and the R&D Return benchmark for 250 software companies. None of this is a price target or a rating. |
Welcome to Golden Door
Learn about the latest technology investments here.
Software Stocks: The Rally Faces Its First Real TestAugust 25, 2026 Software has staged one of the sharper recoveries of the summer. The iShares Expanded Tech-Software Sector ETF (IGV) has climbed roughly 18% since its July 23 low, meaningfully outperforming the Nasdaq 100 and the Magnificent Seven over that stretch. The bounce follows a painful first half in which AI disruption fears compressed valuations across the sector. Investors worried that generative and agentic AI would erode pricing...
ADBE Return on Equity Analysis: Navigating the Digital Media Landscape A daily market insight into Adobe's financial performance, growth prospects, and competitive positioning. 6/10/2025 Daily Market Insights Your daily dose of market intelligence6/10/2025 Return on Equity Scorecard: ADBE Adobe (ADBE): A Creative Powerhouse in a Shifting Landscape Adobe (ADBE) remains a dominant player in the digital media and marketing solutions space, but recent performance reveals a nuanced picture. While...
Navigating Market Turbulence: A Daily Briefing Inflation, Rates, and Recession Risks: Expert Insights for Informed Investing 6/9/2025 Daily Market Insights Your daily dose of market intelligence6/9/2025 Executive Summary The market currently navigates a complex landscape characterized by persistent inflation, rising interest rates, and slowing economic growth, creating a challenging environment for investors. The Federal Reserve's hawkish stance to combat inflation, while necessary, increases...